

This blog is accurate as of 12/10/2026.
Many homeowners are facing, or dreading, the same problem in today’s mortgage market: their remortgage is coming up, and rates are climbing.
If you’re in this situation, we’re here to help. Let’s take a look at what the market is really like right now.
Where mortgage rates are right now
Mortgage rates have climbed sharply in recent weeks. On 5 October 2026, the average five-year fixed rate reached 6.00%, according to Moneyfacts, the first time it has hit that level in around three years. The average two-year fix followed closely at 5.98%. For comparison, the average two-year fix was 4.83% back in January.
What this means if your deal is ending soon
Letting your mortgage roll onto your lender’s standard variable rate (SVR) may take less effort, but it could cost you considerably more. Let’s put this into a real-world example.
Imagine someone took out a five-year fix in 2021 at 2.5%, paying £1,500 a month on a 25-year mortgage. Five years on, they have roughly £283,000 left to repay over 20 years. Here’s how their monthly payments could change if they rolled onto an SVR of 7.5%, or locked in a new two-year fix at today’s average of 5.98%:
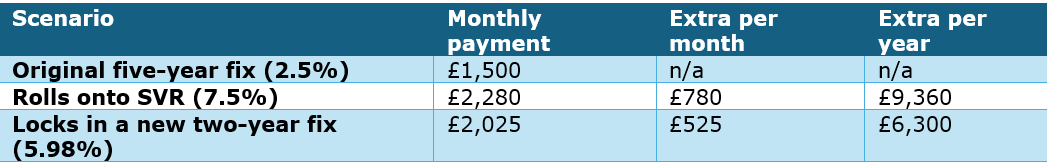
In this example, locking in a new fix rather than rolling onto the SVR would mean paying around £255 a month less, or just over £3,000 a year. However, fees, early repayment charges and personal circumstances all affect which option suits you, so the lowest headline rate isn’t always the best deal overall.
Please note: this example is for illustration only and is based on the assumptions above. It doesn’t include product fees and is not financial advice. Your own figures will depend on your loan size, remaining term and lender.
How early can you lock in a new deal?
Many lenders let you secure a new deal around three to six months before your current one ends. Locking in early can protect you if rates keep rising, and some lenders will let you switch to a cheaper deal if rates fall before your new one starts. Policies vary, so check the terms with your lender or broker.
Mortgage rates are influenced by the Bank of England base rate, inflation and what the markets expect to happen next, which is why they can be hard to predict. A qualified mortgage adviser can help you weigh up your options based on your circumstances.
Product transfer or full remortgage?
When your deal ends, you’ll usually have two routes to choose from.
A product transfer means staying with your current lender and moving onto one of their new deals. It’s often quicker and simpler, as it usually doesn't require a property valuation or legal work. The trade-off is that you’re limited to your existing lender’s range, which may not include the most competitive rates on the market.
A full remortgage means moving your mortgage to a new lender. This opens up the whole market, which could mean a better rate or more suitable terms. It does involve more steps, including a valuation and legal work. A Conveyancer will pay off your existing mortgage, set up the new one and register the change with HM Land Registry. Because this takes time, starting early helps make sure your new deal is ready before your current one ends.
Fixing now or waiting: weighing it up
There’s no one-size-fits-all answer, but these are some of the things worth considering:
- Certainty: a fixed rate means your payments stay the same for the length of the deal, which can make budgeting easier.
- Flexibility: fixed deals often come with early repayment charges if you leave early, while tracker deals can offer more flexibility but your payments will rise or fall with the base rate.
- Length of fix: a shorter fix could let you take advantage sooner if rates fall, while a longer fix gives you protection for longer if they keep rising.
- Your plans: if you’re thinking of moving home or paying off a lump sum in the next few years, this could affect which deal suits you.
Speaking to a qualified mortgage adviser is the best way to find out which option suits your situation.
Steps to take now
- Check when your current deal ends and whether any early repayment charges apply.
- Find out what your current lender would offer on a product transfer.
- Speak to a mortgage adviser or broker to compare deals across the market.
- Gather your documents, such as payslips, bank statements and ID.
- If you’re switching lenders, instruct a Conveyancer early so the legal work doesn’t hold things up.
How Sort can help
If you’re remortgaging with a new lender, our experienced Conveyancers can handle the legal side for you, keeping you updated at every stage so your new deal is in place when you need it. Remortgage Guide UK | Compare Rates & Expert Advice
Email: hello@hellomortgage.co.uk
Tel: 0800 292 2557
Disclaimer: Your home may be repossessed if you do not keep up with mortgage repayments.
Image
Gallery.


